
Kenya’s growing debate over lending practices, interest rates, hidden charges and asset repossession presents an important opportunity to examine how credit can support economic growth without exposing borrowers to unfair treatment.
As the National Assembly’s Finance and National Planning Committee engages companies offering credit and asset financing services over concerns about alleged exploitative practices, attention must also turn to understanding the different financing models available to consumers, including Buy Now, Pay Later (BNPL).
At its core, BNPL is a simple concept: customers acquire goods or assets when they need them and spread the cost over an agreed period. Instead of paying the full purchase price upfront, they make instalment payments according to a financing agreement. When structured responsibly, this model can help households manage significant purchases, enable small businesses to invest in productive equipment and give individuals access to assets that might otherwise remain beyond their immediate financial reach.
However, the convenience of deferred payment should not obscure the financial commitment involved. BNPL is not free money. It is a credit arrangement that creates an obligation for the borrower and a responsibility for the financier. Understanding both sides of this relationship is essential if asset financing is to contribute meaningfully to Kenya’s economic empowerment agenda.
One of the strongest arguments for BNPL is its potential to expand financial inclusion. Access to conventional bank credit can be difficult for individuals who lack substantial savings, formal employment records, conventional collateral or an established credit history. Small businesses and informal-sector operators may have viable economic opportunities but lack the upfront capital required to take advantage of them.
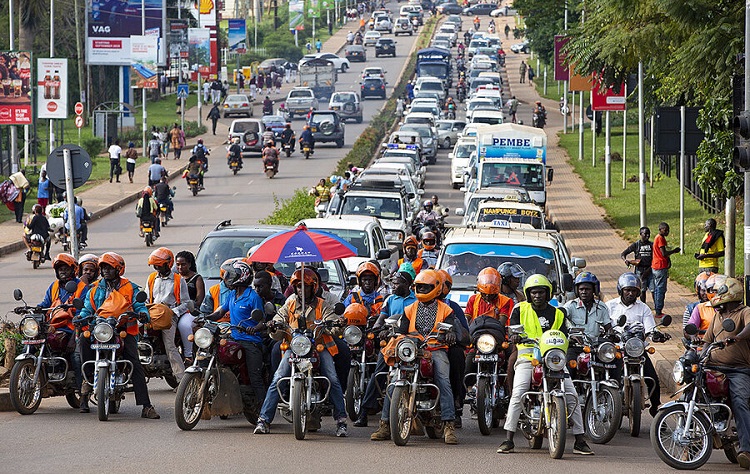
Asset financing offers an alternative route. A boda boda rider, for example, may be able to acquire a motorcycle and begin earning income without having to save the entire purchase price first. A small-scale trader could finance equipment needed to expand operations, while an entrepreneur could acquire machinery that improves productivity. In these situations, financing is not simply about bringing consumption forward; it can provide access to an income-generating asset.
The economic benefits can extend beyond the individual borrower. A financed motorcycle can support transport services, a delivery business or household income. Equipment acquired by a small enterprise can improve output, create opportunities for employment and strengthen local supply chains. When borrowers can repay their financing from income generated through the acquired asset, credit becomes a tool for building livelihoods rather than merely meeting immediate needs.
Nevertheless, these benefits depend on whether the financing arrangement is affordable, transparent and suited to the borrower’s circumstances. Expanding access to credit should not mean encouraging people to take on obligations they cannot reasonably meet.
Understanding the true cost of financing
A common source of misunderstanding in asset financing is the difference between the advertised price of an asset and the total amount payable over the financing period. A customer may focus on the deposit or the weekly or monthly instalment without considering the cumulative cost of the agreement.
Depending on the product and contract, the total cost may include interest, insurance premiums, administrative fees and other disclosed charges. Penalties may also apply when payments are missed, subject to the applicable agreement and law. These costs can make the final amount payable significantly different from the original cash price.
For this reason, responsible financing begins with clear disclosure. Before committing to an agreement, customers should be able to establish the deposit required, the amount financed, the instalment amount, the repayment period and the total amount payable over the life of the facility. They should also understand which charges are compulsory, when they fall due and what consequences may follow if they miss a payment.
For example, a boda boda rider should not assess a financing offer solely by asking whether the daily instalment appears manageable. The more important question is whether the expected earnings from the motorcycle, after accounting for fuel, maintenance, insurance, licensing, household needs and other operating expenses, will leave enough money to meet the instalment consistently.
The same principle applies to traders and other small-business owners. Revenue is not the same as profit, and an asset does not automatically generate sufficient income simply because it has been acquired. A sound financing decision requires realistic projections, an allowance for unexpected expenses and a clear understanding of the repayment obligation.
Financiers also have a responsibility to present information in language customers can understand. Transparency should be a practical standard, not merely a clause buried in a lengthy contract. Where charges, repayment terms or default provisions are unclear, customers should be encouraged to seek clarification before signing.
Borrower responsibility must go hand in hand with lender accountability
Consumer protection is a shared responsibility. Borrowers must take reasonable steps to understand the agreements they enter into, while financiers must ensure their products are presented fairly and that customers are not misled about their obligations.
Customers should carefully review repayment schedules, penalties, insurance arrangements, early settlement conditions and the procedures that apply in the event of default. They should ask what happens if an asset breaks down, business income falls or illness temporarily affects their ability to earn. Where the financed asset is the primary source of income, these questions are particularly important.
Borrowers should also assess their ability to pay during difficult periods rather than relying exclusively on the best-case scenario. Seasonal business fluctuations, rising operating expenses and unexpected family responsibilities can disrupt repayment plans. Building a modest financial buffer, where possible, can help reduce the risk of default.
At the same time, responsible lending requires financiers to assess affordability, explain material contractual obligations and communicate the consequences of missed payments. The fact that a customer qualifies for a facility does not necessarily mean that every repayment amount is appropriate for their circumstances.
The industry must therefore resist the temptation to measure success only by the number of assets financed or customers acquired. Sustainable growth should also be measured by repayment performance, customer understanding, fair complaint resolution and the extent to which financed assets improve borrowers’ economic circumstances.
Repossession should not be the starting point
Asset repossession is among the most sensitive aspects of asset financing because the consequences can extend beyond the loss of property. For a borrower whose motorcycle, vehicle or equipment generates daily income, losing the asset can undermine the very source of money needed to repay the outstanding debt.
This is why repossession should be treated as a last resort, not the first response to repayment difficulties. Where a borrower encounters financial challenges, early communication between the customer and financier can create an opportunity to explore reasonable solutions before the situation deteriorates.
Depending on the agreement, the circumstances and the applicable law, possible options may include restructuring the repayment schedule, agreeing on a revised payment arrangement or considering another appropriate resolution. Such options are not automatic entitlements and will depend on the particular circumstances, but early engagement can make it easier to identify a workable way forward.
Borrowers, for their part, should not wait until arrears have accumulated significantly before contacting their financiers. Ignoring reminders or avoiding communication can narrow the options available and make a difficult situation harder to resolve.
Financiers must equally ensure that any recovery action follows the contract and applicable legal requirements. Customers should understand the circumstances under which repossession may occur, the notices or procedures that apply, and how any outstanding balance will be handled. Recovery practices should be professional, proportionate and consistent with the law.
Importantly, consumer protection does not mean eliminating a lender’s ability to recover an asset or enforce a legitimate agreement. Financiers need predictable mechanisms to manage defaults and protect their businesses. The objective is to ensure that those mechanisms are exercised fairly, transparently and lawfully, with appropriate consideration of the borrower’s circumstances.
Building trust through responsible financing
The National Assembly’s engagement with credit and asset financing providers comes at a time when the sector must demonstrate that expanding access to finance and protecting consumers are complementary objectives rather than competing priorities.
Regulators, policymakers, financiers and consumer representatives all have a role to play. Regulators should promote compliance with applicable consumer protection and credit laws, address misleading practices and ensure that complaints can be resolved effectively. Policymakers should seek a balanced framework that discourages exploitation without unnecessarily restricting access to legitimate financing products.
Financiers should invest in customer education, transparent pricing, responsible affordability assessments and accessible complaint-handling mechanisms. They should also communicate proactively with borrowers experiencing difficulties, rather than allowing manageable repayment problems to escalate into disputes and repossession.
Consumer education must go beyond explaining how to make instalment payments. It should help customers compare offers, calculate the total cost of credit, distinguish business revenue from disposable income and recognise the consequences of default. Better-informed borrowers are more likely to make sustainable decisions, while transparent providers have a stronger foundation for long-term customer relationships.
Ultimately, BNPL should be judged not simply by how quickly it enables someone to acquire an asset, but by whether that acquisition creates lasting value. If financing allows a rider to earn a livelihood, a trader to grow a business or an entrepreneur to improve productivity without imposing an unsustainable debt burden, it can be a meaningful instrument of economic inclusion.
Kenya does not have to choose between expanding access to credit and protecting borrowers. Both objectives can be pursued through clear agreements, fair pricing, informed decisions, responsible lending and lawful debt recovery.
The real measure of a successful financing market is not the number of loans disbursed or assets repossessed. It is the number of customers who can use credit productively, meet their obligations under fair terms and improve their economic circumstances in the process. That is the standard the BNPL sector should work towards as Kenya seeks a more inclusive and accountable financial system.
Related Content: When Is Your Nduthi Due? Here Is Why The Cost Might Balloon If You Are Not Careful